

Last updated:
Contents
Prices, fees and rules in this article were checked on 28 October 2026. They can change, so check the linked pages before you decide.
The digital euro does not exist yet, and you cannot use it in the Netherlands today. The European Central Bank (ECB) says it aims to be ready for a possible first issuance during 2029, provided EU lawmakers adopt the digital euro Regulation in 2026. Before that, the ECB plans a 12-month pilot starting in the second half of 2027. According to the ECB, the participants are 36 selected payment service providers, selected merchants and staff of the ECB and 19 national central banks, not members of the public. The ECB also warns that emails, letters and websites inviting people to invest in the digital euro or to join the pilot are scams. This guide explains what the digital euro would be, the official timeline and what it would mean for cash and privacy.
1. The digital euro at a glance
| Question | Answer from the ECB |
|---|---|
| Can I use it now? | No. A first issuance is aimed for during 2029, if the EU Regulation is adopted in 2026 |
| Is there a pilot? | Planned for 12 months from the second half of 2027, with selected payment service providers, merchants and central bank staff |
| Will it replace cash? | No. The ECB says it would complement cash, which would remain legal tender |
| Would it cost money to use? | The ECB describes it as free of charge for consumers when paying in shops, online or person to person |
| Would it pay interest? | No interest would be paid on digital euro holdings |
| Who decides? | EU lawmakers adopt the Regulation; the ECB decides on issuance only after that |
Source: ECB digital euro overview, pilot page, progress page and FAQs, checked 28 October 2026.
2. What the digital euro would be
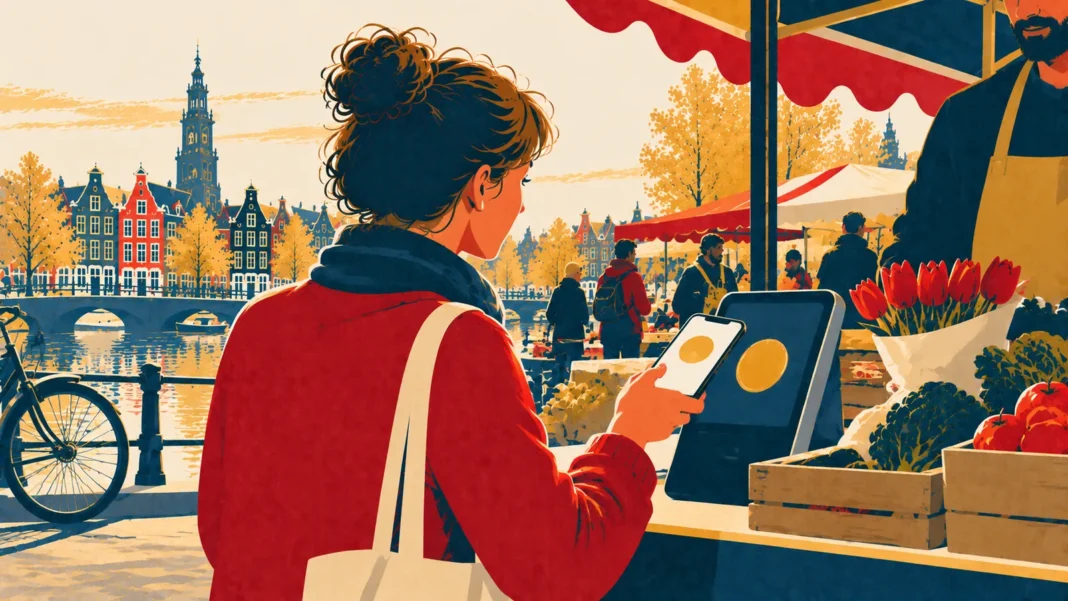
The ECB describes the digital euro as a digital form of cash issued by the central bank, which people could use free of charge in shops, online and from person to person. It would be available both online and offline. According to the ECB’s FAQ, to start using it you would set up a digital euro account through your own bank or another EU payment service provider. You could then pay, for example, by tapping your phone at a shop terminal or by choosing the digital euro at an online checkout and authorising the payment in your banking app.
The ECB lists these intended features:
- Legal tender. The digital euro would have legal tender status. The European Commission’s proposed Regulation foresees mandatory acceptance by any merchant who accepts digital payments, and mandatory distribution by banks to their customers.
- Offline payments. The offline function is meant to work with poor or no network connection, and during temporary power outages.
- Across the euro area. Payments would work in the same way in every euro area country, regardless of which provider you use.
- Inclusion. The ECB says it would be designed to be accessible, including for people with disabilities and people without a bank account.
According to the ECB’s FAQ, the proposed Regulation would make it available to people, businesses and public bodies residing or established in a euro area country, temporarily or permanently, and to visitors travelling to the euro area. That would include residents of the Netherlands.
3. Timeline: from 2020 to a possible launch in 2029
| Date | Step |
|---|---|
| October 2020 | The ECB publishes its “Report on a digital euro” |
| October 2021 to October 2023 | Investigation phase: design and distribution options studied |
| November 2023 to October 2025 | Preparation phase (closing report published 30 October 2025) |
| October 2025 | The ECB Governing Council decides to move to the next phase |
| 2026 | The ECB’s plans assume EU lawmakers adopt the digital euro Regulation in the course of 2026 |
| Second half of 2027 | Planned start of a 12-month pilot |
| During 2029 | Aim for a possible first issuance, if the Regulation is adopted in 2026 |
Source: ECB progress page and pilot page, checked 28 October 2026.
The ECB stresses that it will only decide whether to issue a digital euro once the Regulation has been adopted, and that its preparations remain flexible to follow the legislative process. A target date is therefore not a fixed launch date.
4. The 2027 pilot: who takes part
The ECB says the pilot will test a beta version of the digital euro in real situations, such as in-shop and person-to-person payments, to check that the system is robust, user-friendly and scalable. According to the ECB:
- Payment service providers: more than 50 applied after a call in March 2026, and 36 from across the euro area were selected.
- Merchants: the ECB invited e-commerce and mobile commerce merchants to express interest, with an application deadline of 27 October 2026.
- Central bank staff: staff of the ECB and 19 national central banks will test the beta version in everyday situations, for example paying in a cafeteria.
The ECB pages checked for this guide do not describe a public sign-up for consumers. Any message that says you have been selected for the pilot, or asks for money or personal details to take part, should be treated as a scam (see section 7).
5. Cash, holding limits and interest
Cash. The ECB’s answer to “Would the digital euro replace cash?” is no. It says the digital euro would complement cash, that cash would remain legal tender, and points to the ongoing redesign of euro banknotes as evidence of its commitment to cash. The European Commission’s Single Currency Package, which the ECB welcomes, aims to preserve people’s freedom to choose between cash and the digital euro.
Holding limit. The digital euro is designed with a limit on how much one person can hold. Payments above the limit would be covered automatically through a linked bank account, so you would not need to top up first. The ECB tested hypothetical limits of up to €3,000 per person at the request of the EU lawmakers, and concluded that day-to-day use would not harm financial stability. The final limit is not set in the ECB pages checked for this guide.
Interest. As with cash in your wallet, no interest would be paid on digital euro holdings.
6. Privacy: who would see your payments
The ECB says it is designing the digital euro to offer the highest privacy level of any electronic payment option. Its privacy page states:
- Offline payments: details would only be known to you and the recipient, comparable to cash.
- Online payments: the Eurosystem would not be able to directly link you to your payments. Data available to the ECB would be pseudonymised.
- Your bank: would only access the personal data needed to comply with EU law, such as anti-money laundering rules, and would need your explicit consent to use your data commercially.
- Supervision: the ECB would be supervised by independent data protection authorities.
These are design commitments for a system that is not yet live. The final rules depend on the EU Regulation.
7. Beware of digital euro scams
The ECB warns that it is aware of emails, letters and fake websites asking people to invest in the digital euro or to join the pilot. It states that these are scams and that it never asks people for investments, money or personal information. If you think you have been a victim of fraud, the ECB advises contacting your local police.
For common scams in the Netherlands, see our guide to WhatsApp scams. For your current payment options, our guide to opening a bank account in the Netherlands explains your right to a basic account.
8. FAQ
Can I use the digital euro in the Netherlands now?
No. The ECB aims to be ready for a possible first issuance during 2029, if the EU Regulation is adopted in 2026.
Can I sign up for the digital euro pilot?
The pilot planned for the second half of 2027 involves selected payment service providers, selected merchants and central bank staff. The ECB pages checked do not describe a sign-up for consumers, and the ECB warns that pilot invitations asking for money or personal data are scams.
Will the digital euro replace cash?
No, according to the ECB. It would complement cash, which would remain legal tender.
Will there be a limit on how much digital euro I can hold?
Yes, a holding limit is part of the design. The ECB tested hypothetical limits up to €3,000 per person; the final amount has not been set in the pages checked.
Is the digital euro the same as a cryptocurrency?
No. The ECB describes it as a digital form of euro cash issued by the central bank, with legal tender status.
Would the government see my payments?
The ECB says it would not be able to directly link you to your payments, and that offline payments would only be known to you and the recipient. Your bank would see what EU law requires, such as for anti-money laundering checks.
🇳🇱 Dutch Corner
| Dutch | English | Example |
|---|---|---|
| de digitale euro | the digital euro | De digitale euro bestaat nog niet. (The digital euro does not exist yet.) |
| het contant geld | cash | Contant geld blijft wettig betaalmiddel. (Cash remains legal tender.) |
| het wettig betaalmiddel | legal tender | De euro is een wettig betaalmiddel. (The euro is legal tender.) |
| de centrale bank | central bank | De Nederlandsche Bank is de centrale bank van Nederland. (De Nederlandsche Bank is the central bank of the Netherlands.) |
| de oplichting | fraud, scam | Dit bericht is oplichting. (This message is a scam.) |
| de proef | pilot, trial | De proef begint in 2027. (The pilot starts in 2027.) |
Sources
- ECB: Digital euro overview (checked 28 October 2026)
- ECB: Digital euro pilot (checked 28 October 2026)
- ECB: Progress on the digital euro (checked 28 October 2026)
- ECB: Frequently asked questions on the digital euro (checked 28 October 2026)
- ECB: Digital euro and privacy (checked 28 October 2026)
Free: Netherlands 2027 Money Checklist
Every deadline and number you need before and after 1 January 2027, on two printable pages. Confirm your email and the PDF is yours; we will also email you when the 2027 figures are confirmed.
 Read nextBusiness & FinanceAI Chatbots in Your Dutch Business: What the EU AI Act and the AVG Require